The short answer
A finance check on a vehicle looks up whether a hire purchase, PCP, conditional sale or similar agreement is still recorded against it. If one is, the finance company usually remains the legal owner until it is paid off, and it can try to recover the car even after it has been sold to you. Our check searches licensed data providers' records by registration and is part of the Premium report (£7.99).
Why does money owed on a car matter to the buyer?
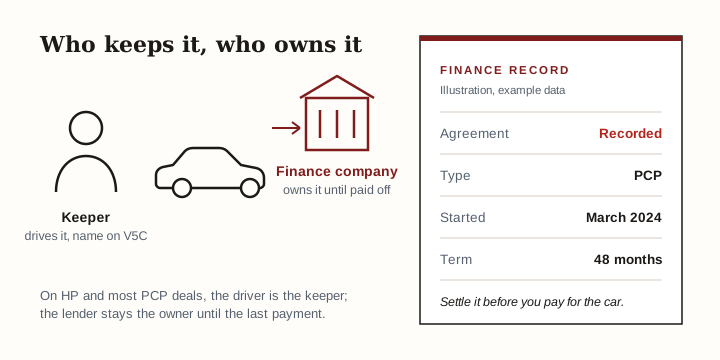
On hire purchase and most PCP deals, the person driving the car is its keeper but not its owner. The finance company keeps ownership until the last instalment, or the optional final payment, has been made, so the car is not the seller's to sell before then.
If you buy it anyway, the lender's claim does not vanish because the car changed hands. It can write to you, ask for the balance or try to take the car back. Nothing on the bodywork, in the advert or in the V5C logbook warns you: the logbook names the registered keeper, which is not the same as the owner.
Which agreements does a finance check on a car find?
- Hire purchase (HP) and conditional sale, where ownership passes to the driver only after the final instalment.
- Personal contract purchase (PCP), where the car stays the lender's unless the balloon payment is made.
- Other finance agreements that a lender has registered against the vehicle.
A personal loan or a credit card used to pay for a car is not tied to the car itself, so it is not registered against it and will not show. A leased car is different again: it belongs to the leasing company for the whole contract and is never the driver's to sell.
What does the finance record in the report show?
- Whether a finance agreement is recorded against the car
- The finance company that holds it
- The type of agreement and the date it started
- How long the agreement runs, where the record gives it
The finance check is one part of the Premium report (£7.99). The same report covers write-off and stolen records, keepers, plate changes, a mileage verdict, a valuation and the full MOT history, which makes it a complete used car history check rather than a finance search on its own. See every part on the sample report.
How do you run a finance check on a car?
- Type the registration and your email address into the form at the top of this page.
- Make sure the make, model and colour shown are those of the car you are looking at.
- Pay for the Premium report (£7.99) by card or PayPal. It opens on screen straight away and a copy is emailed to you.
What should you do if finance is still recorded?
Stop before you pay anything, deposit included. Ask the seller to settle the agreement and to show you the finance company's written confirmation that nothing is owed, then check the registration again before the money changes hands.
A private buyer who buys a car in good faith, not knowing it is on hire purchase or conditional sale, may be protected by Part III of the Hire Purchase Act 1964. That protection does not extend to motor traders, and relying on it can mean a long dispute: finding the record first avoids one.
Questions buyers ask
Is a finance check on a vehicle free?
No. Finance agreements are held on private databases that charge for every search, so the check is part of the Premium report (£7.99). The car's DVLA details and MOT history are free with the look-up at the foot of each page.
Do I need anything more than the registration?
No. The registration finds the car; your email address is only where the report is sent.
Can a lender take a car back from someone who bought it?
It can try. While money is owed under hire purchase or conditional sale, the finance company is usually still the owner, and it may ask the new keeper for the car or for the balance.
Does the V5C logbook show outstanding finance?
No. The V5C shows the registered keeper, the person responsible for the car, not who owns it, and it says nothing about finance.
What if the seller says the finance has been paid off?
Ask for the finance company's settlement letter, then check the registration again. A settled agreement can take a little time to leave the records, so the letter is your proof in the meantime.